by Dr Kelechi Ekuma, Senior Lecturer at GDI
Effective public financial management reform in developing countries is usually approached as a question of appropriately reallocating power across institutions. However, the international evidence points to a much cheaper and more practical solution: reforming the submission deadlines that govern how work moves between institutions. In September, I had the privilege of exploring that idea with the senior officials who lead Nigeria’s public oversight institutions. These are the four lessons I took away.
Two clocks, one process
Section 85(5) of Nigeria’s 1999 Constitution is precise. The Auditor-General for the Federation shall, within ninety days of receiving the Accountant-General’s financial statement, submit his reports to the National Assembly. The ninety days begin on receipt, and nothing fixes the date on which receipt must happen.
A second deadline works differently. Section 49(1) of the Fiscal Responsibility Act 2007 requires the federal government to publish its audited accounts within six months of the year end. It fixes an outcome rather than a handover, and addresses government at large rather than a named officer. In February 2026 the House of Representatives Public Accounts Committee recorded that it held audit reports up to the 2022 financial year only, with 2023, 2024 and 2025 outstanding.
Read together, the two provisions are instructive. One sets an outcome without naming who must deliver it. The other names an officer and allows him a generous ninety days, but leaves the starting date open. Neither gap concerns authority, which is encouraging, because gaps of this kind can be closed administratively.
Why a single date is a development question
Audit matters for development because it closes the loop. A legislature that receives assurance on last year’s capital spending while this year’s budget is still being drafted can act on what it learns; assurance arriving three or four years later cannot. The Open Budget Survey 2023 is more encouraging here than one might expect: Nigeria scores 72 out of 100 on audit oversight, which the survey rates adequate, against 31 for budget transparency. Audit is the comparatively strong part of the system, and what limits its contribution is not capacity but the date on which its work can begin.
An off-the-shelf standard is available. The Public Expenditure and Financial Accountability framework grades countries on exactly this handover: financial reports submitted for external audit within three months of the year end scores an A, six months a B, nine months a C. Nigeria is already assessed against that benchmark, so writing a dated submission rule into the treasury circulars would align practice with a measure the country is judged by anyway, at no fiscal cost. Reforms of this size are easy to overlook, which is rather the point.
Where the idea was tested
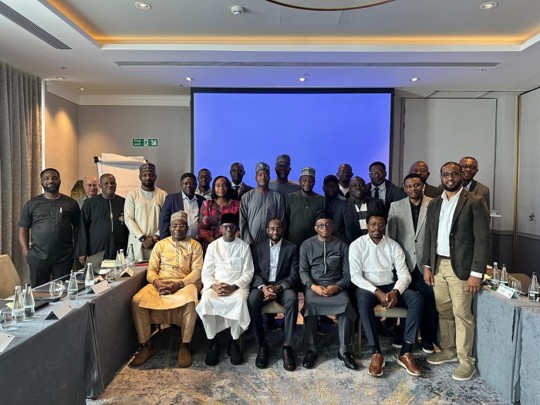
On 14 September 2026, I was invited to facilitate an executive session on stakeholder management and inter-agency coordination for senior leaders from across Nigeria’s public oversight institutions. In the room were the Chairman of the Independent Corrupt Practices and Other Related Offences Commission (ICPC), the Director-General of the Bureau of Public Procurement (BPP), the Director-General of the National Information Technology Development Agency (NITDA), and the Auditor-General for the Federation, together with senior officials from the Office of the Attorney-General of the Federation as well as other senior officials from each of those four agencies.
I was there as an independent facilitator rather than as an adviser to any of the institutions, which is a useful position to hold: comparative evidence arrives with no institutional interest attached, and every claim stands or falls on the expertise in the room. Four lessons came out of the day.
Lesson one: clocks do more work than powers
I brought five jurisdictions to the room, ordered by how legally binding their coordination instrument is. The pattern should encourage any government working within tight fiscal space, because the best performers did not need the strongest instruments.
The United Kingdom’s Digital Regulation Cooperation Forum cannot direct its own members. Its joint advisory service set an eight-week standard and then took between 93 and 169 days. It published that result openly, along with the cause, differing internal sign-off procedures across the four regulators, which turned the standard into a live management target. Estonia connects 612 institutions and moved more than 1.5 billion data requests in a year, on a decree plus a statutory duty never to ask a citizen for the same thing twice. The European Union allocated authority completely, naming a lead supervisory authority in its data protection regulation, and on my reading was the slowest of the five. Its own remedy, seven years on, gave nobody more authority; instead, it attached a clock: fifteen months to a decision, twelve under a simplified route.
The pattern is consistent and, for policymakers, usefully cheap. What separates the strong performers is not legal force but three conditions: a published time standard, one named holder of the file at each stage, and an instrument matched to the conditions it works in. All three are within the gift of administrators.
Lesson two: the opportunity sits in the handovers
The institutions in the room know their mandates better than any outsider. What a comparative view adds is a way of seeing how they fit together. They are not competing gatekeepers duplicating one another’s work but successive control points on a single transaction: NITDA at the concept stage, the BPP at award, the Accountant-General at disbursement, the Auditor-General after the year closes, and the ICPC across all of it. Each does its own work well; none is positioned to see the file end to end. Where time is lost, it is lost between, rather than during, the stages.
That is good news for reform design. The gains are available without reopening anybody’s mandate, and without the lead regulator model so often proposed in such cases, which would reallocate authority nobody is disputing.
Lesson three: questions travel further than frameworks
Nobody in that room needed a governance typology. What proved useful were questions specific enough to act on, attached to machinery that already exists. Three emerged, each building on something the institutions have already built.
The ICPC assessed 344 federal institutions in the 2025 round of its Ethics and Integrity Compliance Scorecard, and names them, which makes it a ready-made vehicle: clearance compliance could sit inside an existing pillar as a sub-indicator, with no new statute. The Accountant-General’s circular of 31 July 2026 already bars any agency from issuing a letter of award unless the covering warrant has been downloaded and attached, so a documentation pack already exists and is already checked. NITDA’s service charter already commits to a decision on IT project clearance within ten working days, so the standard exists and publishing performance against it would be a natural next step.
None of the three requires new money, new legislation or a new body. Each needs only a decision, and each could begin within the current financial year.
Lesson four: specifics make the conversation useful
What earned the room’s attention was not the framework but the detail: section numbers, dates and measured intervals. Eight weeks against 93 to 169 days. Ninety days from an undated receipt. Three, six and nine months in the PEFA grades. Numbers of that kind can be checked on the spot by the people in front of you, which is exactly why they are worth bringing.
Generalities invite polite agreement; specifics invite engagement, and engagement is where the value is created. For colleagues planning this kind of work, do the instrument-level reading first and bring the primary sources with you.
What the session produced
Participants left with a protocol to apply to a live project, written ninety-day commitments, and an online workspace holding the activities, so they can run the same exercises with their own teams. The method was designed to outlast the day and to belong to the institutions rather than the facilitator.
I left with a research question I did not have when I arrived. The clock that never starts is largely absent from the coordination literature, and it now forms the basis of a paper I am developing with colleagues on why legal force predicts coordination performance so poorly. The pattern is unlikely to be Nigeria’s alone. Many public financial management systems across Africa and South Asia inherited the same design, in which a named officer holds a generous deadline that an undated handover controls, so the diagnostic should travel even where the statutes do not. Engagement of this kind is usually described as research reaching practice. Here practice sets the research agenda, which is the more productive direction of travel and a good argument for doing more of it.
Dr Kelechi Ekuma is based at the Global Development Institute, University of Manchester. His expertise covers digital transformation, skills development, human resource development, institutional change and public sector governance in in developing and transitioning contexts, especially sub-Saharan Africa.
Top image: Participants at the executive session on stakeholder management and inter-agency coordination, 14 September 2026.
Note: This article gives the views of the author/academic featured and does not necessarily represent the views of the Global Development Institute as a whole.
Please feel free to use this post under the following Creative Commons license: Attribution-NonCommercial-NoDerivatives 4.0 International (CC BY-NC-ND 4.0). Full information is available here.